
Business contents insurance for storage facilities
General advice only. It does not consider your business's objectives, financial situation or needs. Cover depends on the insurer's policy wording, which you will receive before you decide.
Two kinds of contents under one roof
A storage facility holds its own contents and its customers' goods. They are insured separately, by different people.
Your facility's contents
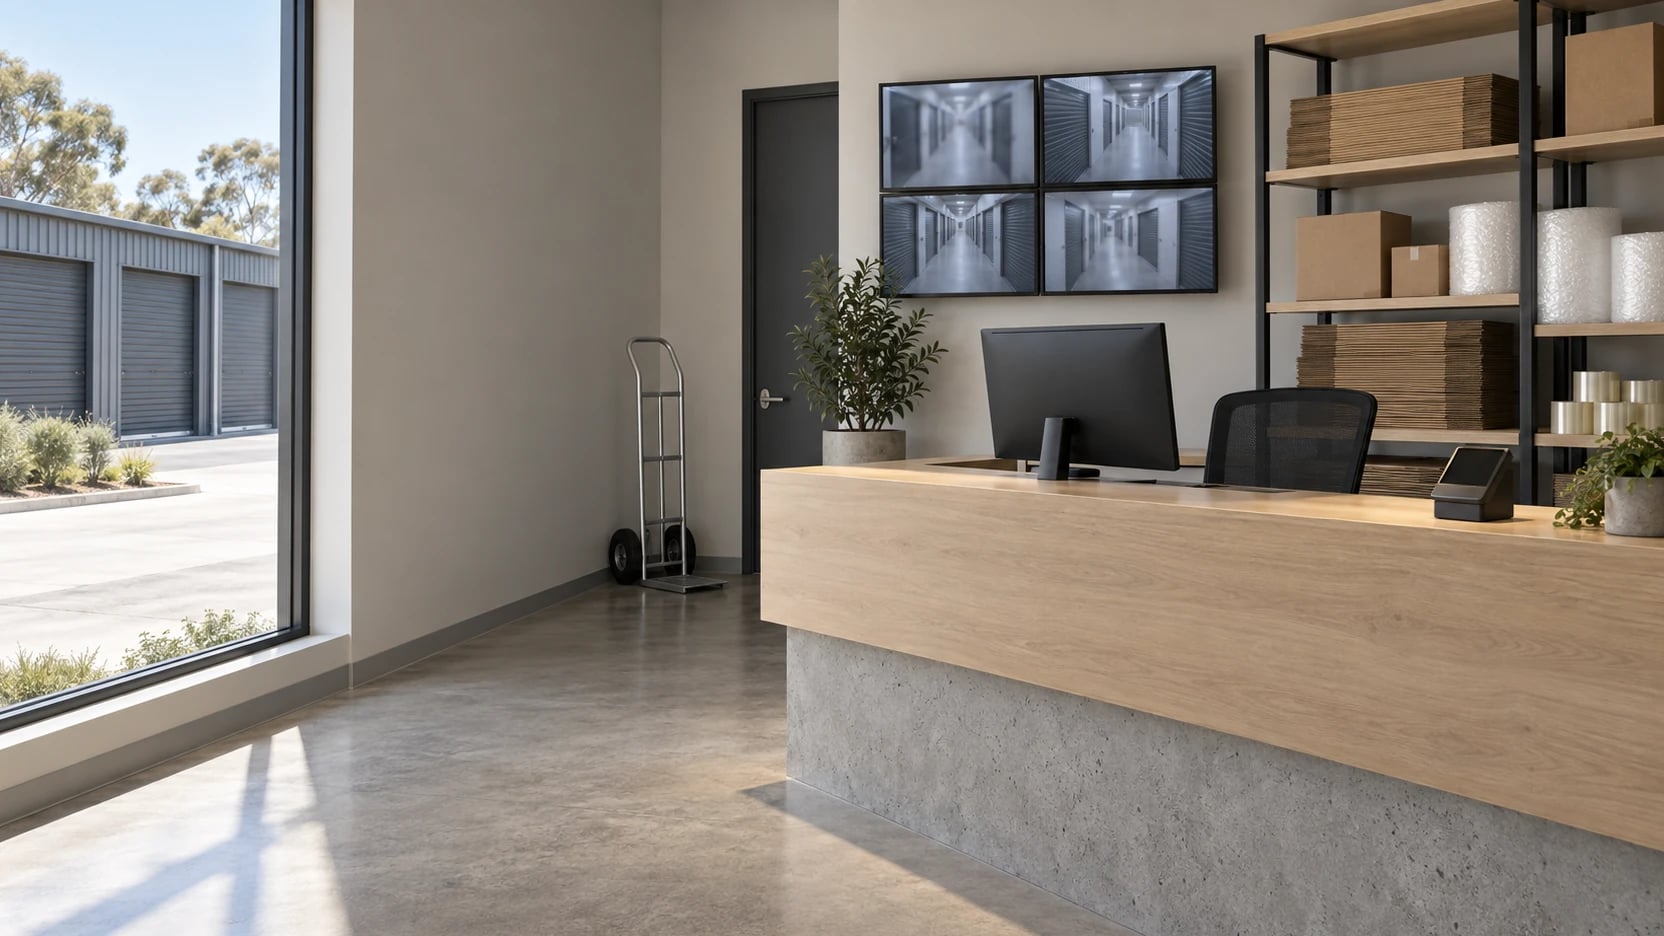
Office furniture, computers and phones, equipment, signage and fit-out, plus any stock the business owns and sells, such as boxes, locks and packing materials.
Your customers' stored goods
The belongings inside each unit are owned by your customers. They can insure them with a policy in their own name.
Storing your own goods? See Goods in Storage insurance
Want to offer your customers that cover? Become an approved facility
What contents cover can include
- Office equipment
- Computers, phones, printers and the other equipment your office runs on, up to the contents sum insured.
- Furniture and fit-out
- Desks, counters, shelving and the fit-out of your office or shopfront, depending on how the policy defines contents.
- Stock you own
- Boxes, padlocks, packing materials and other stock you sell, usually insured with its own sum insured.
- Theft
- Theft is often a separate section with its own sum insured. Conditions, such as signs of forced entry, can apply.
- Specified items
- Higher-value items can be listed individually, each with its own description and sum insured.
- Your policy wording decides
- Each insurer defines contents, stock and theft its own way. The insured events, limits and exclusions are in the policy wording.
How applying works
Contents sits in the property section of the application, which asks for separate sums insured for your contents, stock and theft, and for any items you want listed on their own. See every detail the application asks for.
Gather your figures
Work out what it would cost to replace your contents and stock. An up-to-date list helps.
Complete the application
One online form covers property, contents, business interruption and public liability.
We approach insurers
We use your application to seek cover for your facility from insurers.
Read the policy wording
Before you decide, you receive the insurer's terms, limits and exclusions to review.
General advice only. It does not consider your business's objectives, financial situation or needs. Cover depends on the insurer's policy wording, which you will receive before you decide.
Contents insurance questions
What is business contents insurance?
It covers the physical things a business owns at its premises, such as furniture, equipment, fit-out and stock, against the events a policy lists. The building itself is usually insured under property cover instead.
Does it cover the goods my customers store?
No. Business contents insurance is for what your business owns. The goods in your customers' units belong to them, and they can insure them with their own policy, such as Goods in Storage insurance at an SSIA approved facility.
Is stock insured the same way as equipment?
Often not. Many policies ask for a separate sum insured for stock, because its value can change through the year. The application asks for contents and stock as separate figures.
How do I work out a contents sum insured?
Add up what it would cost to replace your equipment, furniture, fit-out and stock with similar items today. A list with photos and receipts makes this easier, and helps if you ever need to make a claim.
Pair contents with your other cover
Contents is usually arranged with property cover for your buildings. Business interruption can protect the income the site earns.
- Property insurance For the buildings and site your storage business runs from.
- Business interruption insurance For income lost when an insured event stops your facility trading.
- Workers' compensation insurance For the people who keep your facility running.
- All facility business insurance Business insurance for self storage facility owners and operators.
Insure what your business owns.
General advice only. It does not consider your business's objectives, financial situation or needs. Cover depends on the insurer's policy wording, which you will receive before you decide.