Running a storage facility can look straightforward: rent out secure space and look after the site. The reality is more complex. Storage facilities face a wide range of risks that can affect daily operations, reputation and financial stability. That makes business insurance an important part of protecting the business you have built.
At SSIA (Self Storage Insurance Australia), self storage is our focus. Whether you run one small site or several facilities in different locations, the right cover can help protect your property, your staff and your income. This guide covers the main risks, the types of cover owners often consider, and what to check before you choose. What any policy covers always depends on the insurer and the policy wording.
Why insurance matters for storage facilities
Storage facilities hold belongings and stock for many different customers. Even with strong security systems, accidents and unexpected events can happen. A break-in, a fire, a water leak or an injury on site can lead to repair bills, lost income or a claim against your business. Without the right small business insurance, your business could face serious financial pressure.
Depending on the insurer and the policy, business insurance may help with:
- damage to your buildings, equipment and fit-out
- income lost while an insured event disrupts trading
- claims made against your business by customers or visitors
- your obligations to staff who are injured at work
Key risks storage facilities face
Before choosing cover, it helps to understand the risks. Some of the most common include:
Theft and break-ins
Despite CCTV, alarm systems and secure locks, storage sites can still be targeted by thieves. A break-in can damage gates, doors and security systems, and leave you dealing with worried customers.
Fire and severe weather
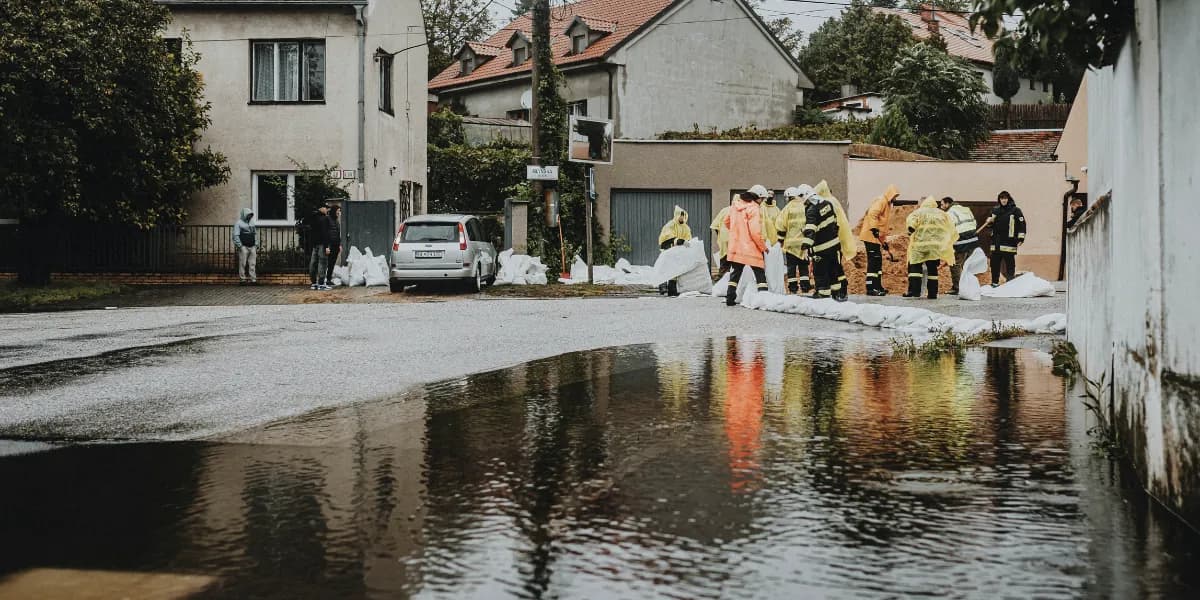
Storage units often hold a mix of furniture, electronics and packaging, so a fire can spread quickly. Storms, bushfires and floods can also damage buildings and cut off access to the site. If your facility is in a flood-prone area, read flood insurance essentials for storage facilities.
Water damage and leaks
Burst pipes, roof leaks or faulty sprinkler systems can cause water damage to buildings and to the units inside them.
Injury to customers and visitors
Customers visit the facility to load and unload their goods. If someone slips, trips or is hurt on site, your business could face a public liability claim.
Injury to staff
Your staff may handle heavy lifting, cleaning and maintenance. Injuries at work can lead to workers' compensation claims.
Covers storage facilities often consider
When a business looks after a site and deals with the public every day, a well-rounded set of covers matters. Here are the main types of small business insurance storage facilities should consider. Not every business needs every cover, and what each one includes depends on the insurer and the policy.
Public liability insurance
Public liability insurance can respond if a customer or visitor is injured, or their property is damaged, because of your business. For example, a customer slips on a wet floor, or a roller door malfunctions. Depending on the policy, it may cover legal costs and compensation you are found liable to pay.
Property insurance
Your buildings, gates, roller doors, security systems and office are valuable assets. Property insurance can cover damage from the events your policy lists, which can include fire, storm and malicious damage. Check that your sums insured reflect what it would cost to repair or rebuild.
Business contents insurance
Customers are usually responsible for insuring the goods inside their own units. Your business still needs protection for its own office equipment, tools, fit-out and stock. Business contents insurance is designed for these, and depending on the policy it may include theft of your business contents.
Business interruption insurance
If an insured event forces your facility to close or limit trading, business interruption insurance may help replace lost income and meet ongoing costs, such as wages and rent, while you recover. In many policies it applies only when the interruption is caused by damage insured under your property cover. Read more about what business interruption insurance is.
Workers' compensation insurance
If you employ staff, you will generally need workers' compensation cover. It deals with work-related injuries and illnesses, such as lost wages and medical costs, under the rules of your state or territory scheme. Because the schemes differ, see our workers' compensation insurance page.
Other covers to ask about
Storage facilities rely on automated gates, lighting, security systems, online bookings and payment platforms. Equipment breakdown and cyber incidents are usually dealt with by separate policies or extensions, not by standard property or liability cover. If these risks matter to your business, raise them when you discuss your insurance.
Your customers' goods need their own cover
Your business insurance protects your facility and your operations. It does not automatically cover the belongings your customers store with you. Many customers assume their items are insured by the facility, which can lead to disputes if something goes wrong.
Encouraging customers to insure their own goods can:
- help them understand where they stand before anything happens
- reduce the chance of a dispute after a loss
- build trust and transparency with the people who rent from you
As an SSIA approved facility, you can give your customers a simple way to insure the goods they store with you, taking out cover online in their own name.
How SSIA works with storage facilities
We arrange cover from insurers for self storage facility owners and operators. Depending on the insurer and policy, that may include property, business contents, business interruption and public liability. One application covers all four, and we use your answers to seek cover from insurers. Workers' compensation is a separate enquiry, because the schemes differ between states and territories.
The insurer's policy wording sets out what each cover includes and excludes, so read it before you decide.
Tips to reduce risk at your facility
Insurance matters, and prevention matters just as much. Some simple steps:
- Install quality security cameras and alarms, and check them regularly.
- Keep walkways clean, dry and free of hazards.
- Schedule regular maintenance for gates, lights, roller doors and locks.
- Inspect roofs, gutters, drainage and plumbing often.
- Provide clear signage and safety instructions for customers.
- Encourage customers to insure their stored goods.
Combining these habits with the right small business insurance helps your facility operate with confidence.
The bottom line
Owning a storage facility comes with responsibilities and risks. Business insurance is not just a box to tick; it is part of how you protect your site, your staff and your income over the long term. Whether you are setting up a new storage business or reviewing the cover you have, start with our facility business insurance page.