For storage facility owners in Australia, managing the risk of natural disasters is part of protecting the business. Floods are among the most unpredictable and costly of them. Whether your facility sits near a river, on the coast or on a floodplain, flood damage can have a serious financial impact.
This guide explains how flood cover for business property generally works, why it varies so much, and what to check if your site is in a flood-prone area. Whether flood is covered, and on what terms, always depends on the insurer, the policy and your location.
How flood cover works for business property
For a business, flood is usually dealt with inside a property or business insurance policy. Depending on the insurer and the policy, flood may be included, offered as an option, limited or excluded.
Policies define flood carefully. A common definition is the covering of normally dry land by water that has escaped from a river, creek, lake, dam or other watercourse. Damage from storm rain, run-off or a burst pipe may be treated differently. Read how your policy defines flood, and which kinds of water damage it covers.
Where flood cover is part of a policy for a storage facility, it may include:
- damage to buildings, units, roller doors and fixtures
- repair or replacement of your own equipment and business contents
- clean-up and debris removal costs
- lost income while the site is closed, if your business interruption cover includes flood
Without flood cover, a single flood could leave you paying for repairs and absorbing lost income at the same time.
Why location matters
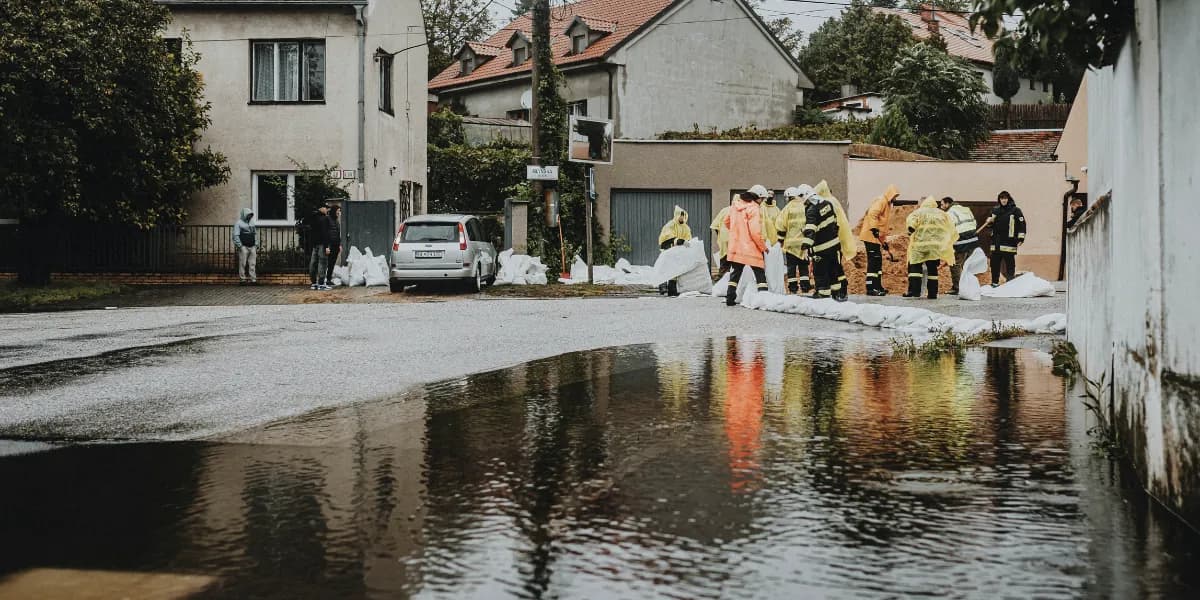
Facilities in low-lying areas, with poor drainage, or close to rivers or the coast face higher flood risk. Even with flood-prevention measures in place, water can be unpredictable. From tropical downpours in the north to flash flooding in the south, flood is a real risk in many parts of Australia.
Location also shapes what insurance you can get. In higher-risk areas, flood cover may cost more, carry a higher excess or come with lower limits, and some insurers may not offer it for some sites at all. That is why it pays to ask early.
Your customers' goods are a separate question
Your facility's insurance is generally arranged for your own business: your buildings, your contents and your income. It does not usually cover the goods your customers store with you. Customers need their own cover for those.
If you are an SSIA approved facility, your customers can take out Goods in Storage insurance in their own name. That cover does not include flood. Under its Product Disclosure Statement (PDS) (PDF, opens in a new tab), flood, meaning water that has escaped from a river, creek, lake, dam, reservoir or canal, is excluded. If your site is flood-prone, be open with customers about it so they can make their own decisions.
Covers to consider alongside flood
Flood is one part of protecting a facility. Depending on the insurer and the policy, other covers may help:
- Business interruption insurance may help with lost income and ongoing costs while the site is closed or limited, when the interruption is caused by insured damage. Check whether flood is one of the events that triggers it.
- Public liability insurance may respond if a customer or visitor is injured on your premises, including during the clean-up after a flood.
How to choose flood cover
- Understand your flood risk. Check flood maps and flood information from your local council and state government, and think about your site's own history.
- Ask how the policy treats flood. Is flood included, optional or excluded? How is it defined? Are there limits, a separate excess, or a waiting period before new flood cover starts?
- Check what else is included. Buildings, your own contents, clean-up costs and lost income may each be treated differently.
- Talk it through. When you apply for business insurance through SSIA, tell us about your site's location and any flood history, and ask about flood directly. Whether flood cover is available for your facility, and on what terms, depends on the insurer.
Reduce flood risk at your site
Insurance helps after a flood. Preparation helps before one.
- Raise switchboards, electrical systems and equipment above known flood levels where you can.
- Keep drains, gutters and stormwater pits clear, and check drainage around the site.
- Maintain roofing, gutters and foundations.
- Keep an emergency plan for staff and customers, including how you will contact customers when a flood warning is issued.
- Keep records of maintenance and risk improvements.
Good risk management may be taken into account by insurers, and it can reduce the damage if a flood does happen.
The bottom line
Floods are unpredictable, and flood cover varies more than most. If your facility is in a flood-prone area, find out exactly how your policy treats flood before the wet season, not after. Read more about property insurance and facility business insurance for storage facilities.